
INVESTMENT RESEARCH REPORT | GOAL 2000 PASSIVE INCOME
GPIQ Strategy & 10-Year Simulation
Income Has a Price: What 2,000 Shares of GPIQ Deliver – and Give Up – Versus QQQM Over Ten Years
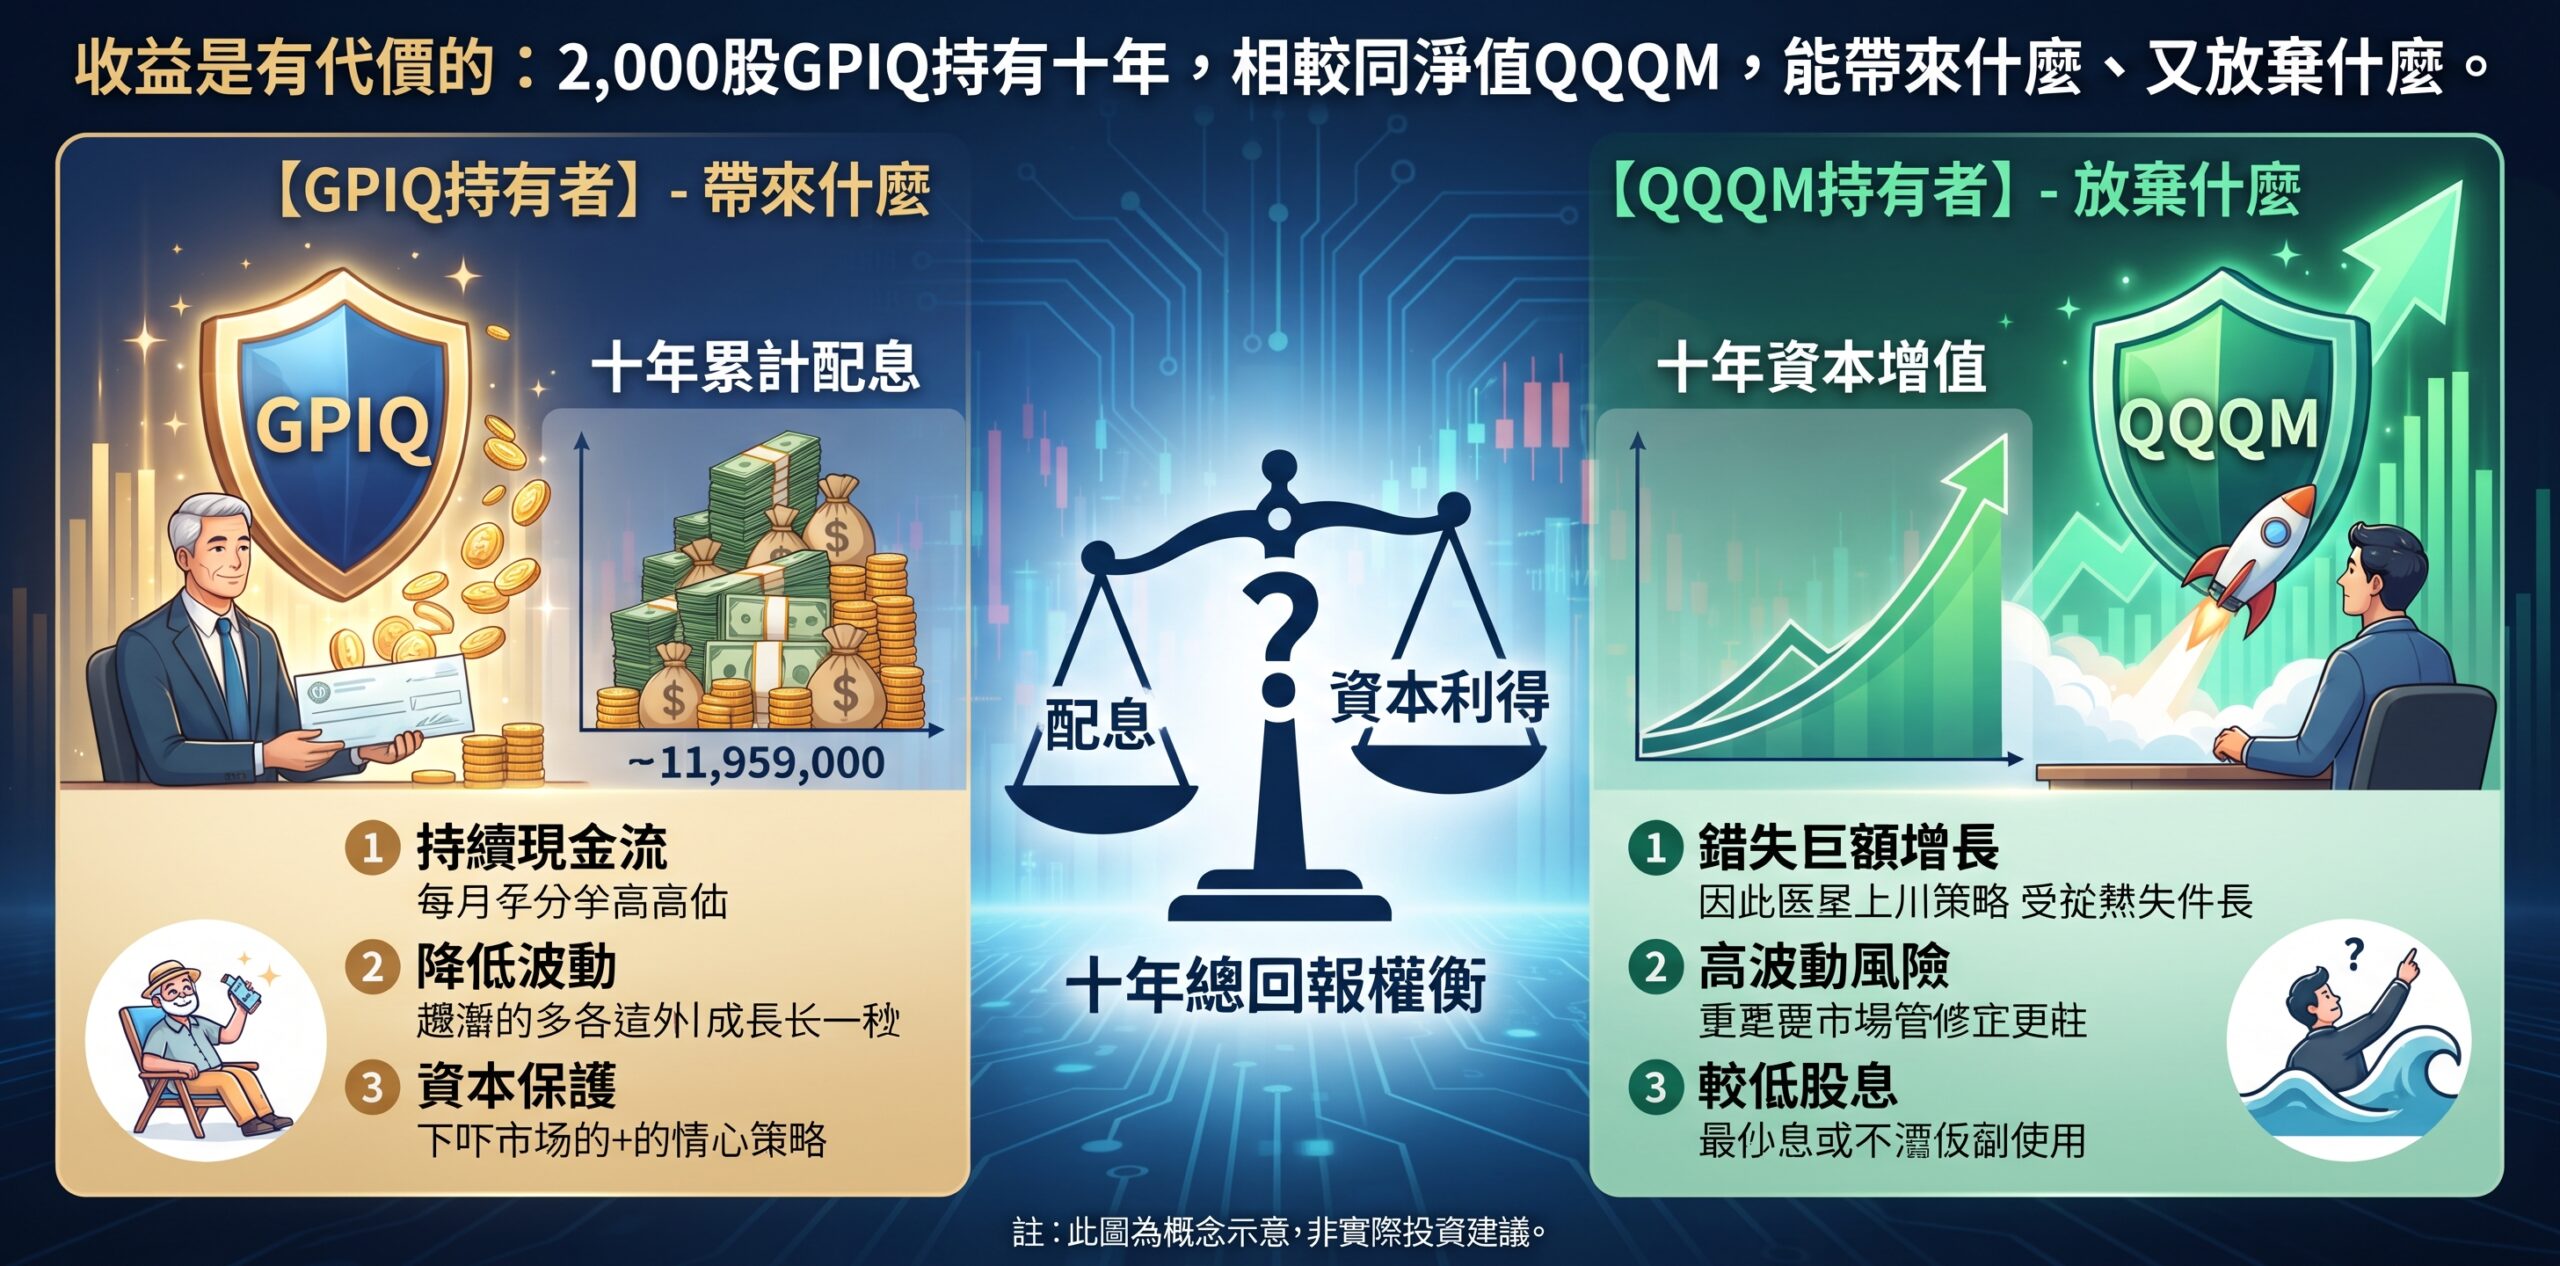
收益是有代價的:2,000股GPIQ持有十年,相較同淨值QQQM,能帶來什麼、又放棄什麼
Report date: 19 October 2026 | Base price: GPIQ $56.58 per share | Simulation position: 2,000 shares ($113,160) | Language: English primary, Traditional Chinese secondary
Executive summary: GPIQ trades terminal wealth for cash flow
GPIQ (Nasdaq-100 High Income ETF) holds a Nasdaq-100 equity portfolio and writes call options dynamically to fund a monthly distribution of roughly 9-10% a year. A 20,000-path Monte Carlo simulation over ten years puts the median total-return terminal value of a $113,160 position at $593,000 for GPIQ versus $675,000 for an equal-value QQQM holding—a median gap of about $82,000. GPIQ finishes ahead in only 11.6% of paths.
If distributions are taken as cash instead of reinvested, the picture changes in form, not in substance: GPIQ’s median price-only value after ten years is $251,000 versus $642,000 for QQQM, but the holder has collected roughly $240,000 of cumulative cash distributions along the way. GPIQ is therefore best understood as a cash-flow engine, not a compounding engine.
重點結論:GPIQ是「現金奶牛」,不是「複利引擎」。含派息再投入的中位終值落後QQQM約$82k,勝率僅11.6%;若派息全數領走,十年累計現金約$240k,但本金中位僅剩$251k。
- $593k: GPIQ median 10-yr value, distributions reinvested
- $675k: QQQM median 10-yr value, distributions reinvested
- 11.6%: Share of simulated paths where GPIQ beats QQQM
- ~$240k: Cumulative cash distributions over 10 years, if taken as cash
Bottom line for the income plan. The $2,000/month target needs an engine that pays. This report quantifies what that engine costs in forgone compounding, so the position can be sized with open eyes: growth must come from QQQM and SCHD, while GPIQ’s job is to pay the monthly bill.
How GPIQ works: dynamic call writing on a Nasdaq-100 portfolio
GPIQ’s strategy has two parts. The first is a full Nasdaq-100 equity portfolio – the same growth-heavy universe that QQQM tracks passively. The second is an actively managed options overlay: the managers sell call options against the portfolio, varying strike and tenor with market conditions, and pass the premium through as a monthly distribution.
Why this is not QYLD-style mechanical overwriting
- Strike and tenor are discretionary. QYLD mechanically sells at-the-money index calls each month, capping upside by construction. GPIQ’s overlay is managed flexibly, which in practice has preserved materially more upside participation.
- The target is partial, not total, overwrite. The aim is to monetise a slice of the portfolio’s volatility while keeping most of the equity exposure intact.
- Distribution rate: roughly 9-10% annualised, paid monthly. The rate floats with option premiums and market volatility; it is not a fixed coupon.
- Expense ratio: 0.29% per year.
策略解析:GPIQ 並非 QYLD 式每月機械賣出平值call,而是主動管理履約價與天期,目標是在保留大部分股票敞口的同時,把部分波動率變現為每月派息。費用率0.29%,年化配息率約9-10%,隨權利金與波動率浮動,並非固定票息。
The tax character: return of capital (ROC) 資本返還
A large share of GPIQ’s distributions has been characterised as return of capital rather than ordinary income—96.4% ROC in the fund’s 2025 actual characterisation. For a non-US investor holding through Interactive Brokers, the practical consequences are:
- The 10% withholding applied upfront on the distribution is partly refunded automatically in the following February-March, once the ROC portion is confirmed. No application is required.
- ROC is tax deferral, not tax exemption: amounts treated as returned capital reduce cost basis, which increases the capital gain realised on an eventual sale.
- At the planned 2,200-share target, the estimated annual refund effect across GPIQ and DIVO combined is in the order of a few hundred US dollars a year – helpful, but not a reason by itself to hold the fund.
稅務特性:GPIQ 派息有很大比例屬資本返還(2025年實際定性96.4%為ROC)。IBKR預扣10%後,ROC過扣部分會在翌年2-3月自動退回,無需申請;但ROC是遞延而非免稅,退回金額會降低成本基礎,未來賣出時資本利得相應增加。
What 36 months of real history show: less return, a smoother ride
GPIQ’s live record runs from October 2023 to October 2026. Over those 36 months the fund did what its design promised: it gave up part of a strong bull market’s upside, and in exchange it fluctuated less and drew down less than QQQM.
| Metric (Oct 2023 – Oct 2026) | GPIQ | QQQM | Reading |
| Total return, annualised (distributions reinvested) | 24.72% | 28.11% | Lag of about 3.4 pts / year |
| Price return only, annualised | 12.77% | 27.35% | Distributions consume roughly half the NAV rise |
| Upside capture vs QQQM | 84.3% | 100% | Keeps most, not all, of up months |
| Downside capture vs QQQM | 76.4% | 100% | Falls less in down months |
| Volatility, annualised | 13.91% | 17.25% | Noticeably smoother path |
| Maximum drawdown in window | -8.71% | -10.07% | Smaller peak-to-trough loss |
| Correlation with QQQM | High by construction – same underlying index | 0.996 over the 36 months (see Appendix A). |
The asymmetry is the product: 84.3% upside capture against 76.4% downside capture is favourable, but in a market that rises far more often than it falls, even a favourable ratio compounds into a total-return lag.
36 個月實證:GPIQ 含息年化24.72%,落後QQQM的28.11%約3.4個百分點;不含息僅12.77%。上行捕獲84.3%、下行76.4%,波動與最大回撤都較低——路走得比較平,但在牛市裡累積落後。
Ten years, simulated 20,000 ways: a median $82k gap with reinvestment
The simulation starts from 2,000 shares at $56.58—$113,160 of market value and runs 20,000 bootstrapped ten-year paths. Nasdaq monthly returns are resampled from 2010-2026, and GPIQ’s path in each scenario is modelled from its empirical capture profile (84.3% upside, 76.4% downside) with a distribution rate of about 9% a year. QQQM is modelled on the same resampled index paths, so the comparison is path-by-path, not two unrelated averages.
| 10-year outcome (median of 20,000 paths) | GPIQ | QQQM | Gap |
| Distributions reinvested – terminal value | $593,000 | $675,000 | -$82,000 |
| Distributions reinvested – annualised | 18.0% | 19.6% | -1.6 pts |
| Distributions taken as cash – price-only value | $251,000 | $642,000 | -$391,000 |
| Price only – annualised | 8.3% | 19.0% | -10.7 pts |
| Cumulative cash distributions received (GPIQ, cash case) | Approximately $240,000 over ten years | – | – |
| Share of paths where GPIQ finishes ahead (total return) | 11.6% | – | – |
Note on percentile bands. This table reports medians only. The full P10 / median / P90 results from the same simulation are set out in Appendix A.
十年模擬(20,000條路徑):含派息再投入中位終值GPIQ $593k vs QQQM $675k,差距約$82k;扣除派息只看本金,GPIQ中位$251k,同期累計領取派息現金約$240k。完整的P10/中位數/P90分位結果見附錄A。
What this means for a $2,000/month income plan
In the adopted plan, GPIQ is the income engine: a 2,200-share target (about $125,000 at the base price, roughly 27% of the planned $461k portfolio) is expected to supply the majority of the $24,000 a year of distributions, with SCHD, DIVO, SGOV and QQQM supplying the rest. This simulation prices that decision.
Read the trade-off in cash terms
- The income is real, and so is its cost. Per 2,000 shares, the median path exchanges about $82,000 of terminal wealth for about $240,000 of cash received over the decade in the take-as-cash case. For a plan whose purpose is monthly cash flow, that can be a rational exchange provided it is made knowingly.
- GPIQ wins in choppy and falling markets. The 11.6% of winning paths are concentrated in sideways and down scenarios, where the option premium cushions the fall. If the next decade extends the AI-led bull market, the lag will likely exceed the median; if it is a turbulent decade, GPIQ’s defence earns its keep.
- Do not ask GPIQ to compound. Its median price-only growth is about 8.3% a year against 19.0% for QQQM. In portfolio language: GPIQ is the cash cow, QQQM and SCHD are the growth engines. Confusing those roles is how an income plan quietly underperforms.
- Concentration is the residual risk. At target size, more than a quarter of the portfolio rides on one covered-call fund on one index. ROC-heavy distributions in a prolonged bear market would erode NAV at the same time as the premium cushion is thinnest relative to losses.
對計劃的含義:GPIQ在$461k計劃中佔約27%,是$2,000/月目標的引擎。這份模擬把代價量化——用約$82k 的中位終值財富,換取十年約$240k的現金流。增長的任務要交給 QQQM 與SCHD,不要期待 GPIQ 本金複利。
Sizing implication. Nothing in this simulation argues against holding GPIQ; it argues for holding it at the planned size for the planned reason – monthly income – and for reviewing the position if the distribution rate, capture profile or ROC character changes materially, rather than adding to it as a growth holding.
Assumptions and limitations: read the medians as a range, not a forecast
- Bootstrap sample is bull-market heavy. Resampling 2010-2026 Nasdaq monthly returns (about 19.4% annualised for the sample) flatters absolute terminal values for both funds. The relative gap between GPIQ and QQQM is the robust output; the dollar levels are optimistic.
- Only 36 months of GPIQ history. Capture rates are estimated from a rising-market sample. In consecutive strong rally years, calls can be run over harder than the model assumes, widening the lag; in flat years the reverse holds.
- Distribution rate held at about 9%. Actual distributions float with premiums and volatility. A sustained lower rate reduces both the cash case’s $240,000 and the reinvested case’s terminal value.
- Taxes are described, not modelled. ROC deferral and the annual withholding refund are favourable to GPIQ in practice but are not credited in the simulation, which is therefore mildly conservative for GPIQ on an after-tax basis.
- No financing cost. Margin interest, if the position is carried with leverage at any point, would reduce both funds’ outcomes and is excluded.
- Full percentile output is in Appendix A. The P10 / median / P90 terminal values, the path-by-path gap distribution and the empirical GPIQ-QQQM correlation coefficient (0.996) are reported in Appendix A.
Method in one paragraph
Starting value $113,160 (2,000 shares at $56.58, the market price on the analysis date, 19 October 2026). 20,000 paths; monthly Nasdaq returns bootstrapped from January 2010 to October 2026; GPIQ modelled path-by-path using its empirical upside capture of 84.3% and downside capture of 76.4% versus QQQM, with distributions of about 9% a year either reinvested or taken as cash. Empirical inputs are the fund’s live record from October 2023 to October 2026. Figures in this report are medians of the simulated distribution unless stated otherwise.
假設與局限:抽樣池為 2010-2026 超級牛市樣本,絕對金額偏樂觀,相對差距方向穩健;GPIQ僅3年歷史,捕獲率來自牛市樣本;9%配息率假設可維持;ROC 稅務遞延未計入模型;未扣除融資成本。本報告為研究分析,不構成投資建議。
Disclaimer. This report is research and record-keeping for a personal portfolio plan. It is not investment advice, a solicitation, or a guarantee of future results. Simulations are hypothetical, are sensitive to the assumptions listed above, and do not represent actual trading.
Sources: fund strategy and distribution characterisation as summarised in the underlying analysis conversation of 19 October 2026, empirical capture, volatility and drawdown figures from the same analysis (Oct 2023 – Oct 2026); Monte Carlo outputs (20,000 paths) from the same analysis. Plan context: $461k portfolio plan, GPIQ target 2,200 shares, adopted 17 October 2026.
Appendix A: Full percentile results from the ten-year Monte Carlo simulation
This appendix reports the complete percentile output of the ten-year Monte Carlo simulation run on 19 October 2026: 20,000 paths, starting value $113,160 (2,000 shares at $56.58). P10 is the 10th percentile of the simulated terminal values—one path in ten finished at or below it—and P90 is the 90th percentile. The medians below are the exact simulation outputs; the rounded medians in the main text ($593k, $675k, $251k and $642k) are the same figures.
附錄A:十年蒙地卡羅完整分位數。本附錄列示2026年10月19日模擬的完整分位輸出:20,000條路徑,起始淨值 $113,160 (2,000股×$56.58)。P10為模擬終值的第10百分位(每十條路徑約有一條不高於此值),P90 為第90百分位。下表的中位數為模擬的精確輸出,與正文的約數($593k、$675k、$251k、$642k)為同一組數字。
Table A1 – Ten-year terminal values: P10, median and P90
| Terminal value after 10 years | P10 | Median | P90 |
| GPIQ – distributions reinvested | $333,971 | $593,092 | $1,042,902 |
| GPIQ – distributions taken as cash (price only) | $141,073 | $250,528 | $440,533 |
| QQQM – distributions reinvested | $331,501 | $674,773 | $1,353,594 |
| QQQM price only | $315,373 | $641,944 | $1,287,738 |
Read across the bands, the shape of the trade-off is visible at every percentile. With distributions reinvested, GPIQ’s P10 ($333,971) is marginally above QQQM’s ($331,501) – the downside cushion at work – while its P90 ($1,042,902) sits well below QQQM’s ($1,353,594), because the call overlay caps the strongest rallies. In the price-only case GPIQ trails at every percentile shown, which is the arithmetic counterpart of the cash distributions paid out along the way.
表 A1 解讀:含派息再投入時,GPIQ的P10($333,971)略高於QQQM($331,501),反映下行緩衝;但P90($1,042,902)明顯低於QQQM($1,353,594),因為賣出 call 限制了最強升浪的參與。扣除派息只看本金時,GPIQ 在各分位均落後,這正是沿途派出現金的對應面。
Table A2 – GPIQ minus QQQM, path by path
| Terminal-value gap (GPIQ – QQQM) | P10 | Median | P90 | GPIQ win rate |
| Distributions reinvested | -$310,823 | -$80,644 | +$3,304 | 11.6% |
| Price only (distributions taken as cash) | -$847,021 | -$390,624 | -$174,222 | 0.0% |
Table A2 is the distribution of the gap computed within each simulated path, so its median need not equal the difference between the two medians in Table A1. With reinvestment, even the P90 gap is only +$3,304: in nine paths out of ten GPIQ finished at or behind QQQM, consistent with the 11.6% win rate in the main text. On a price-only basis GPIQ did not finish ahead in any simulated path (win rate 0.0%), and even its P90 gap remained -$174,222 – before counting the cash distributions the holder received, which is precisely the income the price-only view excludes.
表 A2為每條路徑內先計算 GPIQ減QQQM 的差距、再取分位數,因此其中位數未必等於表A1兩個中位數之差。含派息再投入時,連P90差距亦僅+$3,304,即十條路徑中約有九條GPIQ終值不高於QQQM,與正文11.6%的勝率一致。扣除派息只看本金時,GPIQ 在所有模擬路徑中均未勝出(勝率0.0%),P90差距仍為-$174,222;但此口徑未計入持有人沿途領取的派息現金,而那正是只看本金時被排除的收入部分。
Correlation
The empirical correlation between GPIQ and QQQM monthly returns over the 36 months from October 2023 to October 2026 was 0.996. The two funds are, to a close approximation, the same underlying exposure; the simulation’s differences come from the options overlay and the distribution stream, not from diversification between them.
相關性:2023年10月至2026年10月的36個月實證月報酬中,GPIQ 與QQQM 的相關係數為0.996。兩者在本質上是近乎相同的基礎敞口;模擬中的差異來自選擇權覆蓋策略與派息流,而非兩者之間的分散效果。
Source: ten-year Monte Carlo simulation, 19 October 2026, 20,000 paths, starting value $113,160 (2,000 shares at $56.58); empirical correlation from the 36-month live record, October 2023 – October 2026. Percentiles are of the simulated terminal-value distribution and are hypothetical, not a forecast.